
Inter Banking & Money Transfer
- Rating
- 4.4
- Downloads
- 50.00M
- Content Rating
- Everyone
Inter Banking & Money Transfer - Screenshots
Inter Banking & Money Transfer - Description
- App Name
- Inter Banking & Money Transfer
- Package Name
- br.com.intermedium
- Developer
- Banco Inter SA
- Category
- Finance
- Last Updated
- May 4, 2016
- Version
- 26.14
Analysis by TrendiApps
I came away from Inter Banking & Money Transfer with a clear impression: it is most useful when you want one financial app to handle several everyday jobs, rather than a separate tool for each one. Developed by Banco Inter SA, this free finance app brings digital banking, investing and international money transfers into the same general experience. That combination is its main argument, but it is also the source of its biggest weakness: an all-in-one banking app can feel less focused than a specialist service.
I would recommend it to someone who wants to reduce the number of financial apps on their phone and is comfortable managing different kinds of money activity from one account. I would be more cautious about recommending it to a person who wants a very simple payment wallet, a dedicated investment platform with deep analysis, or a transfer service used only occasionally. In my experience, the app makes the most sense when several of its functions are relevant at the same time.
What the app is really like to use
Inter Banking & Money Transfer is a digital banking app in the finance category, but describing it only as a banking tool undersells its wider purpose. The store summary presents it as an all-in-one service for banking, investing and international transfers. That matters because the practical benefit is not one spectacular feature; it is the ability to move between ordinary banking tasks and broader financial planning without constantly changing apps.
The app is free to install and carries an Everyone content rating. It was released on May 4, 2016, and its current version is 26.14, with Android support from version 7.0 onward. Those details make it accessible to people using older Android devices, although I would still keep the operating system updated for general banking security and compatibility.
Its scale also suggests that this is not a niche experiment. The app has passed 50 million installs and holds a 4.4 average from around 4.9 million ratings. I do not treat popularity as proof that every person will enjoy the interface, but it does indicate that Banco Inter SA has built a service used by a very large audience.
The first useful way to think about it is as a financial hub. A conventional bank app usually concentrates on balances, payments, transfers and account administration. An investment app tends to focus on portfolios and market information. An international transfer service normally centers on sending money across borders. Inter attempts to put these areas close together, which can be convenient for someone whose financial life crosses those boundaries regularly.
That convenience is especially noticeable in a realistic monthly routine. Imagine receiving income, paying household expenses, setting aside part of the balance for an investment, and sending money to a family member abroad. With separate providers, I would need to check several balances, remember different login details and move money between services. With this app, the attraction is being able to begin from one banking environment and handle those related decisions in a more connected way.
Stories You Might Enjoy
Gallery’s Quiet Advantage: It’s Already Where Your Photos Live
Universal TV Remote Control Gets the Basics Right, but Setup Needs Work
Instagram’s Real Advantage Is Keeping Every Kind of Attention in One Place
Shadow Fight 3 Makes Every Duel a Lesson in Timing
Pizza Ready! Makes the Dinner Rush Feel Good—Until It Doesn’t
AliExpress Makes Curiosity Shopping Worth the Search
There is a subtle advantage here that a short store description cannot show: the app is more valuable as a workflow than as a single feature. If you use only one part of it, its broader design may not matter. If you regularly combine banking with investing or international transfers, the reduced switching can become a genuine time saver.
Banking for people who want fewer separate tools
The everyday banking side is likely to be the starting point for most users. I found the all-in-one approach appealing because it encourages me to look at ordinary spending and longer-term money decisions in the same place. That can make it easier to notice when a balance is sitting unused or when a planned transfer will affect money reserved for bills.
Still, this design requires discipline. A single app containing several financial areas can make the home experience feel busy, particularly for someone who only wants to check a balance or complete a basic payment. The more options an app places near the main banking functions, the more important it becomes to know exactly what action I am taking before confirming it.
My practical advice is to establish a simple routine rather than explore randomly. I would first learn where the core banking actions are, then identify the areas for investing and international transfers. After that, I would use the app with a specific purpose each time: checking available money, preparing a transfer, reviewing an investment decision or dealing with a cross-border payment. That approach reduces the chance of treating the service like a casual shopping app.
Another useful habit is separating “money I can spend” from “money I am considering for another purpose.” An all-in-one interface can make the total balance look reassuring even when part of it is intended for bills, investments or a recipient abroad. The app can bring these activities together, but it cannot replace personal budgeting. I would still keep a small written plan or spreadsheet if my monthly finances are complicated.
Investing without leaving the banking environment
The investment component is one of the most interesting reasons to choose this app over a basic bank application. I like the idea of reviewing investment decisions alongside the account from which money is allocated. It creates a more realistic picture than looking at an investment balance in isolation, because I can consider upcoming expenses and available cash before committing funds.
That said, convenience should not be confused with depth. Someone who wants advanced research, detailed portfolio construction or a highly specialized investment interface may prefer a dedicated investment platform. An integrated banking app is better suited to people who value access and continuity over a professional trading workspace.
A non-obvious trade-off is that the same centralization that makes investing easier to start can also make it feel deceptively simple. Moving from a normal account screen to an investment option may require less effort than opening a separate brokerage account, but the financial decision itself still deserves research. I would use the app to organize and access investments, not as a substitute for understanding risk, time horizon or liquidity.
For a cautious user, the best workflow is to decide the purpose of the money before opening the investment section. Is it intended for a near-term expense, a longer-term goal or simply money that does not need to remain immediately available? Answering that first helps prevent the convenience of the app from becoming an excuse for impulsive choices.
International transfers and the questions that matter
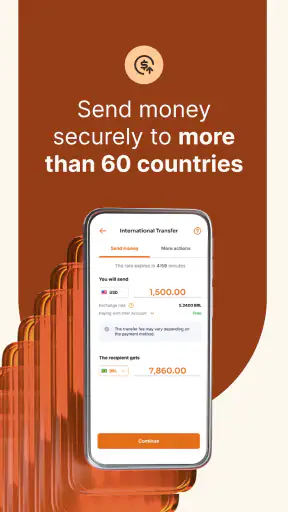
International money transfers are another reason this app can stand apart from an ordinary domestic banking tool. If I need to send money across borders, having that option within the same financial environment is more convenient than starting from a completely separate service. It is particularly relevant for people who support relatives abroad, receive money internationally or manage expenses in more than one country.
Before using this part of the app, I would check the recipient details carefully and review the full transaction summary before confirming. International payments can involve exchange-rate considerations, timing differences and information that must match the recipient’s account. Even when the interface is clear, the user remains responsible for entering accurate details.
The important question is not simply whether the app supports international transfers; it is whether it is the best choice for the particular transfer. A specialist remittance service may be preferable when the user’s only goal is sending money abroad and the service offers a more familiar process for the destination country. A traditional bank may feel more appropriate for someone who wants branch support or already manages all international activity there.
I also would not assume that the convenience of one app automatically means every transfer is the cheapest or fastest option. Those details can depend on the route, currency and transaction conditions. I would compare the final amount received and the total cost with the usual alternatives before sending a large payment. The app is strongest when integration matters; comparison shopping remains sensible when the transfer itself is the main priority.
Where the all-in-one design starts to struggle
The meaningful weakness is focus. Banking, investing and international transfers serve different mental needs. Banking asks for speed and clarity. Investing asks for context and careful consideration. International transfers ask for precision and confidence about the destination. Combining them can be practical, but it can also make the app feel like a collection of financial departments rather than one perfectly unified experience.
I would be especially careful if I were introducing the app to a family member who is not comfortable with financial technology. The number of available areas may create uncertainty about which balance is available for spending, which action moves money, and which decisions have longer-term consequences. In that situation, a simpler banking app may be easier to teach, even if it offers fewer services.
There is also a psychological downside to putting investing so close to everyday banking. When I open an app to check a payment, I may be shown opportunities to think about money beyond that immediate task. For some people, that is useful encouragement. For others, it can create distraction or pressure. I prefer to review investment options at a planned time instead of mixing them with routine account checks.
Another limitation is that an app cannot remove the complexity of financial life merely by placing everything on one screen. International transfers still require careful recipient information. Investments still involve uncertainty. Everyday banking still depends on budgeting and account security. The central interface is convenient, but it should not encourage the belief that complicated decisions have become risk-free.
Who should choose it, and who should look elsewhere?
I think the best audience is someone who wants a broad digital banking relationship and expects to use more than one of the app’s main areas. It suits people who prefer handling routine banking and financial planning from one place, especially when international transfers are part of their normal life. It can also appeal to users who are tired of moving money between a bank, an investment service and a separate transfer provider.
It is less suitable for someone who wants only the simplest possible account interface. If all you need is a quick balance check and occasional domestic payments, the extra financial sections may add more visual noise than value. In that case, a stripped-down banking app could be the better choice.
I would also point experienced investors toward a specialist platform if detailed analysis and advanced investment tools are their main priorities. The same applies to frequent international senders who compare providers carefully for each corridor. Inter can be the more convenient central option, but convenience is not always the same as specialization.
For older Android users, the minimum operating system requirement of Android 7.0 is helpful because it does not force everyone onto a recent device. Even so, I would avoid using any banking app on a phone that no longer receives security updates when a safer device is available. Compatibility is only one part of a secure setup.
New users should also take time to verify the developer name before installing. The official developer is Banco Inter SA. Since financial apps deal with sensitive activity, I would not rely on a similar-looking name or an unofficial download source. After installation, I would use a strong device lock, keep the app and operating system updated, and avoid completing financial actions on an untrusted network.
My verdict after weighing convenience against control
My final view is positive, with an important condition: Inter Banking & Money Transfer is best when its breadth matches the way you manage money. Its strongest quality is not that it performs one banking task in an extraordinary way. It is that it brings banking, investing and international transfers into one free app from Banco Inter SA, giving users a connected place to organize several parts of their financial routine.
The app’s large audience, 50 million-plus installs and 4.4 average rating show that it has broad appeal, while its Everyone rating makes it approachable as a general finance product. I would not use those figures as a guarantee of a perfect experience, because interface preferences and financial needs vary widely. They do, however, support the impression that this is an established option rather than a narrowly focused newcomer.
What I appreciate most is the possibility of reducing friction between everyday money management and larger financial plans. What holds me back is the risk that the all-in-one structure may feel crowded or may encourage users to move too quickly between simple banking actions and more consequential decisions.
If I were recommending it to a friend, I would say this: choose it if you want a broad digital banking home and will genuinely use its investment or international-transfer capabilities. Start with the basic banking workflow, learn where each financial area sits, and compare important international transactions before confirming them. If you want a minimalist account app or a deeply specialized investment or remittance service, another option may serve you better.
For the right user, the app is a practical financial hub rather than just another mobile bank. For the wrong user, its range can become unnecessary complexity. That distinction is the key to deciding whether Inter Banking & Money Transfer deserves a place on your phone.
Inter Banking & Money Transfer FAQ
What is Inter Banking & Money Transfer, and what can I use it for?
Inter Banking & Money Transfer is a mobile finance app designed to help users manage banking-related activities and send money electronically. Depending on the supported country, bank, and service partners, it may allow you to transfer funds, review transaction details, and access other payment features from your phone. Available tools can vary by region, so check the app’s current description before downloading.
Is Inter Banking & Money Transfer safe to use for sending money?
The app may include standard security measures such as account authentication, encrypted connections, transaction confirmations, and security notifications. However, no financial application is completely risk-free. Download it only from an official store, use a strong password or device lock, and never share verification codes, banking credentials, or personal identification details with anyone claiming to provide support.
Does Inter Banking & Money Transfer charge fees for transactions?
Transfer fees can depend on several factors, including the destination bank, transfer method, currency, transaction amount, and your location. Some transfers may be free, while others can include service, exchange-rate, or receiving-bank charges. Review the final confirmation screen carefully before approving a payment, because fees and exchange rates may change and are not necessarily identical for every transaction.
How long do transfers take with Inter Banking & Money Transfer?
Transfer times depend on whether the transaction is domestic or international, the participating banks, weekends and public holidays, compliance checks, and the selected payment method. Some payments may arrive almost immediately, while others can take one or more business days. If a transfer remains pending, check its status in the app and contact official support rather than submitting repeated payments.
What should I do if I enter the wrong recipient or a transfer fails?
Check the recipient’s name, account number, routing information, and transfer amount before confirming any transaction. If you make a mistake, contact the app’s official support channel and your bank as quickly as possible; cancellation is not always available once processing has started. For failed or delayed payments, save the transaction reference, review the error message, and avoid sharing sensitive information through unofficial channels.
Pros
- Fast transfers between supported banks and accounts
- Clear transaction history makes payments easy to track
- Useful for managing multiple banking services in one app
- Transfer status updates help confirm successful payments
- Convenient access to banking features while traveling
Cons
- Some transfers may incur fees depending on the bank or method
- Availability of features can vary by country and financial institution
- Identity verification may take time for new users
- Requires a stable internet connection for most transactions
- Occasional maintenance can temporarily limit access to services


